¶ 3201
Overview
Insurance as a holding vehicle. Chapter 14 treated insurance as a shield: liability coverage that pays claims so that the client's own assets are never reached (see supra ch. 14). Chapter 12 treated the cash value of life insurance and annuities as exempt property under state law (see supra ¶¶ 1240, 1250). This chapter treats insurance in a third role, as a wrapper: a life insurance policy or annuity contract, usually privately placed and often issued by a foreign carrier, whose separate account holds an investment portfolio. The wrapper may defer or eliminate income tax on the portfolio's returns, may pass the portfolio to beneficiaries free of income tax at death, and may, under the law of the carrier's jurisdiction or the policyholder's home state, place the portfolio beyond the reach of the policyholder's creditors.
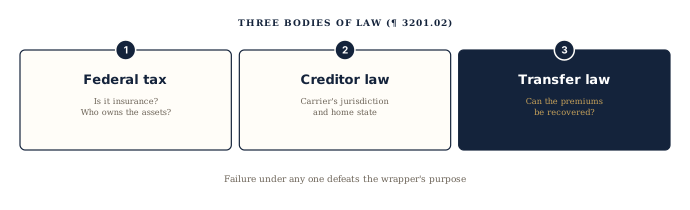
Three bodies of law. A wrapper must satisfy three bodies of law at once, and failure under any one of them can defeat the purpose of the arrangement. The first is federal tax law, which decides whether the contract is life insurance or an annuity at all, whether the policyholder is treated as owning the underlying investments, and what reporting and excise obligations arise. The second is the creditor-protection law that applies to the contract, which may be the law of the carrier's jurisdiction, the law of the policyholder's domicile, or both. The third is fraudulent transfer law, which decides whether the premium payments themselves can be recovered by creditors. The planner must also consider the law governing any trust that owns the policy.
Scope. The chapter addresses private placement life insurance (PPLI) and private placement variable annuities (PPVA) issued to United States persons and their trusts, including policies issued by carriers in Bermuda, the Cayman Islands, Liechtenstein, Luxembourg, Switzerland and the Isle of Man. It does not address ordinary retail life insurance or annuities, which are covered by chapters 12 and 14, or captive insurance companies, covered in chapter 14 (see supra ¶ 1480).
A caution on authority. The reported decisions on wrappers are almost entirely tax decisions. A search of publicly available case law located no reported United States decision in which a court considered a foreign PPLI policy, a Swiss annuity or a Liechtenstein policy in a bankruptcy, contempt or turnover proceeding. The creditor-protection analysis in this chapter therefore rests on statutes and on decisions involving domestic policies, and its conclusions should be treated as less certain than those in chapters that rest on decided cases.
Organization of the chapter. Paragraph 3210 describes the structure of a wrapper. Paragraphs 3220 and 3230 address federal tax qualification and the investor control doctrine. Paragraph 3240 addresses excise tax, passive foreign investment company issues and reporting. Paragraph 3250 addresses creditor protection under the law of the carrier's jurisdiction, and ¶ 3260 addresses creditor protection under state exemption statutes. Paragraph 3270 addresses premium payments as fraudulent transfers. Paragraph 3280 addresses the wrapper within a larger protective structure, and ¶ 3290 places wrappers in the Threat Matrix.