¶ 1401
Overview
Scope of the chapter. This chapter examines how the profits and losses of an LLC are shared among its members and how its cash and other property reach them. It addresses the statutory defaults that apply when the operating agreement is silent, the circumstances in which a member has a right to receive a distribution, the solvency limits that protect the LLC's creditors, the liability of members and managers for distributions made in violation of those limits, tax distributions and their treatment when a member's interest is subject to a charging order, the federal income tax rules that govern allocations in outline, and the structure of distribution waterfalls. It closes with a drafting checklist.
Two different questions. The law distinguishes between allocation and distribution. An allocation assigns profits and losses to members, usually by entries in their capital accounts, and for an LLC classified as a partnership it determines each member's share of taxable income. A distribution is a transfer of money or other property by the LLC to a member on account of the member's interest. The two are linked, because in a well-drafted agreement the capital accounts that record allocations determine what each member receives on liquidation. They are nonetheless distinct. A member may be allocated income without receiving any cash, and a member may receive cash without any corresponding allocation of income. Much of the drafting described in this chapter is directed to keeping the two in an intended relationship.
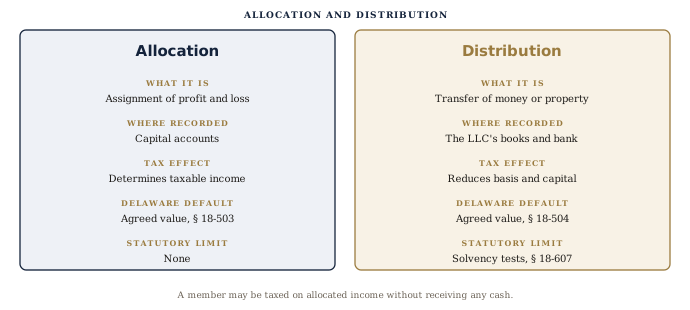
The role of the statute. The Delaware act and the uniform act take different approaches. The Delaware act supplies defaults for both allocations and distributions, measured by the agreed value of each member's contributions. Del. Code Ann. tit. 6, §§ 18-503, 18-504. The uniform act supplies a default rule for distributions only, and requires distributions before dissolution to be made in equal shares. Rev. Unif. Ltd. Liab. Co. Act § 404(a) (2013). Both statutes impose mandatory limits on distributions that would leave the LLC unable to meet its obligations, and both make those limits enforceable against members who receive distributions knowing that they were improper. Del. Code Ann. tit. 6, § 18-607; Rev. Unif. Ltd. Liab. Co. Act §§ 405–406 (2013). Most of the economic arrangement, however, is left to the operating agreement.
Organization. The chapter proceeds in nine parts: the statutory defaults (¶ 1410); the right to distributions (¶ 1420); the limitations on distributions (¶ 1430); liability for wrongful distributions (¶ 1440); tax distributions (¶ 1450); tax payments when a member's interest is charged (¶ 1460); tax allocations (¶ 1470); waterfalls, redemptions and non-pro-rata distributions (¶ 1480); and a drafting checklist (¶ 1490). Contributions and capital accounts are examined supra ch. 13, preferred returns and financing infra ch. 16, and the partnership tax rules in detail infra chs. 40 and 41.